Black Scholes Model
26 Jul 2025
Bachelier
Black scholes model
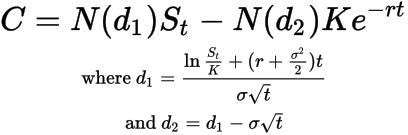
Basic intuition
N(d1)St: Return: The value of the stock you receive contingent on the option finishing in the memory.N(d2)Ke-rt: Cost: This is just the probability that the option hits timed by the exercise price, discounted back to now.d2represents the probability that the option will be exercisedd1hedge ratio of an option: its the distance of stock price from strike over normalised vol timeKe-rtjust how much we get if we exercise the option
Black 76
Why have a black scholes model for commodities? It has fall backs.
- theres a risk free interest rate
- underlying follows brownian motion
- But vol and drift are considered constants!
- no dividends
- No arbs
- No transaction costs
Noticed that BSM didn’t work for commodities. Agricultural product underlying rise before harvest and fall after, oil usually rises during winter and falls during summer.
So just use BSM for futures instead of pointing it directly at the underlying spot.


Honestly not that different.
Appendix
BSM
- brilliant.org/wiki/black-scholes-merton
- investopedia.com/terms/b/blackscholes
- financetrainingcourse.com/education/wp-content/uploads/2011/03/Understanding.pdf
- gregorygundersen.com/blog/2024/09/28/black-scholes
- benjaminwhiteside.com/2021/01/15/black-76
- researchgate.net/publication/228318867_An_Intuitive_Understanding_of_the_Black-Scholes_Formulas
- notion.moontowermeta.com/the-intuition-behind-the-black-scholes-equation
B76